 ultimate-guide
Real Estate Market Trends Hobbs 2026: A Guide
Table of Contents
- Real Estate Market Trends in Hobbs: Where Things Stand in 2026
- Hobbs Home Prices 2026: Current Data and Year-Over-Year Movement
- Hobbs Home Valuation: How to Determine What Your Property Is Worth
- Hobbs Days on Market: What Speed of Sale Tells You About Conditions
- Hobbs Housing Inventory: Supply Levels and What They Mean for Buyers and Sellers
- Reconciling Conflicting Market Data: Why Numbers Don't Always Align
- Practical Guidance: Should You Buy, Sell, or Wait in 2026?
- Frequently Asked Questions
Last Updated: October 5, 2026
Real Estate Market Trends in Hobbs: Where Things Stand in 2026
The real estate market trends Hobbs is experiencing right now tell a clear story about local conditions, buyer behavior, and what's ahead for 2026. At Rodney Davis - No-Nonsense Realtor, we track these trends daily through live MLS data.
The Hobbs housing market sits at an inflection point: prices, inventory, and sales speed have all shifted. For buyers that means opportunity and pressure; for sellers, understanding actual conditions rather than outdated assumptions.
This guide breaks down the real estate market trends Hobbs is showing right now, explains why online sources report conflicting numbers, and gives practical guidance on whether 2026 is your year to buy, sell, or sit tight.
Hobbs Home Prices 2026: Current Data and Year-Over-Year Movement
Home prices in Hobbs have moved noticeably over the past year. Median sold price reflects where the market settled after shifts in demand and inventory, and year-over-year changes vary by property type and neighborhood.
Price data is tricky because median sold price, median listing price, and median home value are three different measurements, what homes closed for, what sellers ask, and an estimate.
The real estate market trends Hobbs shows include seasonal variation: spring sales command different prices than winter closings. Year-over-year comparisons account for this; month-over-month changes can be volatile on few transactions.
Recent closings tell the most reliable story, what buyers actually pay, not what sellers hope for. For valuing your home or setting an offer price, sale data beats estimates every time.
Hobbs Home Valuation: How to Determine What Your Property Is Worth
Your home's value depends on what similar properties recently sold for, not what an algorithm estimates. AVMs like Zillow's Zestimate are convenient but often wrong by thousands, especially in smaller markets like Hobbs with fewer comparable sales.
The right way to value your home is a comparative market analysis (CMA): find similar homes that sold recently nearby, adjust for square footage, condition, and lot size, and arrive at a realistic range.
If you're selling, get a professional valuation before you list.
For buyers, valuation tells you whether a listing is realistic. If nearby homes sell for $180,000 and a similar property is listed at $210,000, the seller is out of touch, useful when deciding whether to offer or move on.
Hobbs Days on Market: What Speed of Sale Tells You About Conditions
Days on market (DOM) is how long a home sits listed before closing, one of the most honest metrics because it reflects actual buyer behavior, not estimates.
Homes selling in under 30 days signal strong demand relative to inventory: sellers have leverage, multiple offers are common, and prices hold or rise.
Hobbs housing market conditions vary by price point and condition: a well-priced, well-maintained home moves faster than one needing work or priced above market. Neighborhood matters too, based on local demand and school district appeal.
For sellers, DOM tells you whether pricing and presentation are working.
For buyers, a home that's sat a long time offers negotiating room, the longer it sits, the more motivated the seller, and the better your chance a lower offer gets accepted.
Hobbs Housing Inventory: Supply Levels and What They Mean for Buyers and Sellers
Citywide averages hide what actually affects your decision.
That's why the most useful inventory read is ZIP-level. Hobbs is served primarily by 88240 (the city core), 88242 (north and northeast growth corridors), and 88244.
Entry-level and upper price bands behave differently.
Price band matters as much as ZIP. A practical way to read it:
- Lower price band: Watch months of supply closely. When it drops below 3, expect multiple-offer situations and limited negotiating room. When it climbs above 4, expect sellers to start covering closing costs or reducing price.
- Middle price band: This is usually the most balanced band. Months of supply in the 3-to-5 range is normal, and negotiation is about condition, inspection items, and timing rather than headline price.
- Upper price band: Supply tends to run higher and days on market longer. Buyers here often have more room to negotiate, request repairs, or ask for concessions.
For sellers, price against the correct ZIP-and-band comp set, not the citywide median.
For buyers, track whether active listings in your target ZIP and band are rising or falling month over month.
One more layer: new construction. When builders are active in a corridor, new-home inventory competes directly with resale in the same price band, lengthening days on market for resale homes that aren't updated and giving buyers an option that doesn't appear in a resale active-listing count. Factor that supply into your read.
The bottom line: inventory isn't a single citywide number. It's a set of numbers by ZIP and price band, and the one that matters matches the property you're buying or selling.
Reconciling Conflicting Market Data: Why Numbers Don't Always Align
Zillow, Redfin, and local MLS data don't always agree on prices, inventory, or trends. It isn't a conspiracy, it's a data problem.
Different sources use different definitions and time periods.
The MLS (Multiple Listing Service) is the most reliable source because it's where actual transactions happen: every licensed realtor enters data, closed sales are verified, pending sales are tracked, and inventory counts are current.
Online tools like Zillow aggregate MLS data but apply their own algorithms, introducing error.
For the real estate market trends Hobbs, the most accurate picture combines MLS closed sales data with professional market analysis.
Practical Guidance: Should You Buy, Sell, or Wait in 2026?
The answer depends on your situation, and on three things most market articles skip: what's actually driving demand here, what ownership costs per month, and how much of any "2026 forecast" is observed data versus projection.
What is actually driving demand
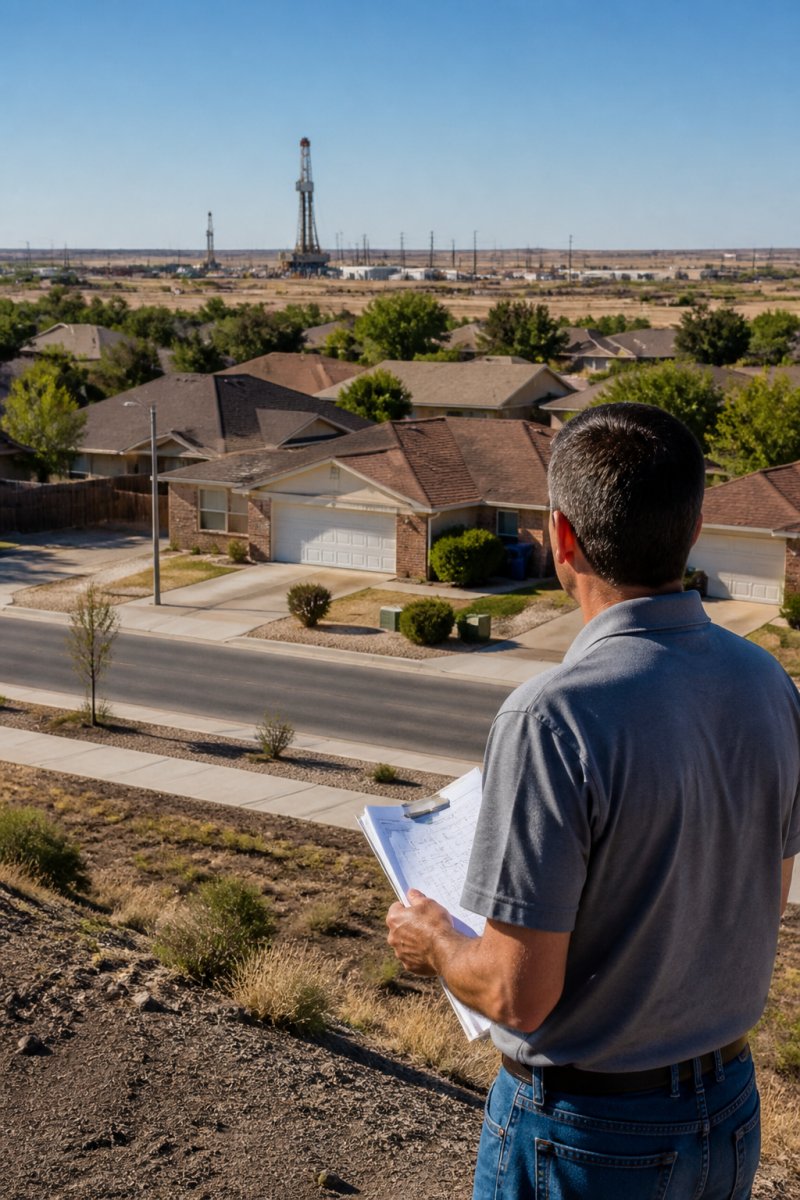
Housing demand here is tied to employment, income, and population. The dominant driver is the energy sector, oil and gas activity in the Permian Basin. When energy is strong, employment, wages, and in-migration rise and housing demand follows; when it softens, the reverse happens, sometimes quickly. A second, steadier driver is the regional healthcare, education, and retail base, which is less cyclical.
That means local housing demand is more sensitive to a single industry than in a diversified metro. If you're buying, ask how your job and income would hold up in a softer energy cycle; if you're selling, know that your buyer pool partly depends on that same cycle.
What ownership actually costs per month
A purchase price is not a monthly payment. To budget realistically, add property taxes, homeowners insurance, and, if applicable, mortgage insurance and HOA dues to the mortgage. Property taxes are set at the county level and vary by jurisdiction and exemptions, so the effective rate isn't one number for everyone, and insurance here runs above the national average because of wind and hail exposure.
A practical way to build your number:
- Start with the loan amount (price minus your down payment).
- Apply the current mortgage rate for your loan type and term to get principal and interest.
- Add monthly property tax (annual tax divided by 12).
- Add monthly homeowners insurance (annual premium divided by 12).
- Add mortgage insurance if your down payment is under 20 percent on a conventional loan, or the applicable FHA mortgage insurance premium.
- Add HOA dues if the property has them.
- Add a maintenance reserve, a common rule of thumb is 1 percent of price per year, divided by 12.
Run that on two or three price points in your target ZIP and band. The gap between "I can afford this price" and "I can afford this payment" is often tens of thousands of dollars. A pre-approval tells you the maximum, not the comfortable number, set your own ceiling below it so a rate change or tax reassessment doesn't wreck your budget.
Separate observed data from forecast
Most "2026 market trends" content blends what has already happened with what someone expects to happen. Keep them apart.
Observed data, closed sales, active listings, days on market, price per square foot for completed periods, is verifiable and what you should anchor on. Forecast data is a projection built on assumptions about rates, inventory, and demand, and is only as good as those assumptions.
A responsible forecast states its assumptions and gives scenarios rather than one number. A three-scenario frame works well:
- Base case: Mortgage rates hold near current levels, inventory stays roughly where it is, and prices move modestly in whichever direction the most recent closed-sale trend shows.
- Higher-rate case: Rates rise, affordability tightens, buyer pool shrinks, days on market lengthen, and negotiating leverage shifts toward buyers.
- Lower-rate case: Rates fall, affordability improves, more buyers enter the market, competition increases, and sellers regain some leverage.
None of these is a prediction, they're the conditions under which your buy-or-sell math changes. If your decision only works in the lower-rate case, it's a bet, not a plan.
The decision
Buy if: The property meets your needs, the full monthly cost fits with room to spare, you'll stay at least 3 to 5 years, and your income would survive a softer energy cycle.
Sell if: Your circumstances changed, relocation, family size, retirement, maintenance burden, or you have a better use for the equity.
Wait if: You're unsure what you want, can't yet cover the full monthly cost including taxes and insurance, face uncertain job security, or are speculating on price.
If you're relocating for work, live MLS listings, professional valuations, and step-by-step guidance are available remotely. If you're a first-time buyer, we walk you through the process so you know what to expect.
Frequently Asked Questions
What are the current housing market trends in Hobbs for 2026?
The real estate market trends in Hobbs reflect broader regional patterns shaped by local economic activity in the Permian Basin. Current conditions show moderate price movements, with inventory levels that vary seasonally. Buyers should expect competitive conditions in desirable neighborhoods, while sellers benefit from steady demand. Days on market typically range from 30 to 60 days depending on price point and property condition. Working with a local agent who understands neighborhood-specific trends helps you navigate these conditions accurately.
How can I estimate my home's value in Hobbs?
Professional home valuation in Hobbs requires analysis of recent comparable sales, property condition, location within the market, and current market conditions. Online estimates from aggregator sites often miss local nuances and can be significantly off. A licensed agent with access to live MLS data and local market knowledge can provide a written valuation that accounts for neighborhood trends, lot size, and recent price movements in your specific area. This approach is more reliable than automated estimates and gives you confidence in listing or buying decisions.
How long does it take to sell a home in Hobbs?
Days on market in Hobbs varies based on price, condition, and market segment. Well-priced homes in desirable neighborhoods typically sell within 30 to 45 days, while homes requiring repair or priced above comparable sales may take 60+ days. Market inventory levels and seasonal demand also affect speed of sale. Strategic pricing from day one and professional marketing reduce time on market significantly. Local market expertise helps you set realistic expectations and avoid overpricing, which is the most common reason homes linger.
Is 2026 a good time to buy or sell a home in Hobbs?
Timing depends on your personal circumstances and local market conditions. Buyers benefit from moderate inventory levels and stable pricing in 2026, though affordability varies by neighborhood. Sellers face steady demand but should avoid overpricing. First-time buyers should focus on finding the right home at fair value rather than timing the market perfectly. Sellers should list when their property is market-ready and priced competitively. Working with an agent who understands neighborhood-level trends helps you make decisions based on data rather than speculation about future price movements.